4 min read

Online Payments Explained: How Digital Payment Options Support Receivables

Online Payments Explained: How Digital Payment Options Support Receivables
Online Payments Explained: Digital Receivables Benefits
8:28

Online payments are a standard part of how consumers and businesses pay bills, invoices, loans, and other obligations. Whether paying a utility bill, making a loan payment, or setting up a recurring transaction, customers expect convenient ways to pay online.

For businesses and financial institutions, the value goes beyond convenience. What happens after a customer makes a payment matters, too. Digital payment options can help streamline receivables, reduce manual processing, improve payment visibility, and make it easier to manage incoming funds.

What Are Online Payments?

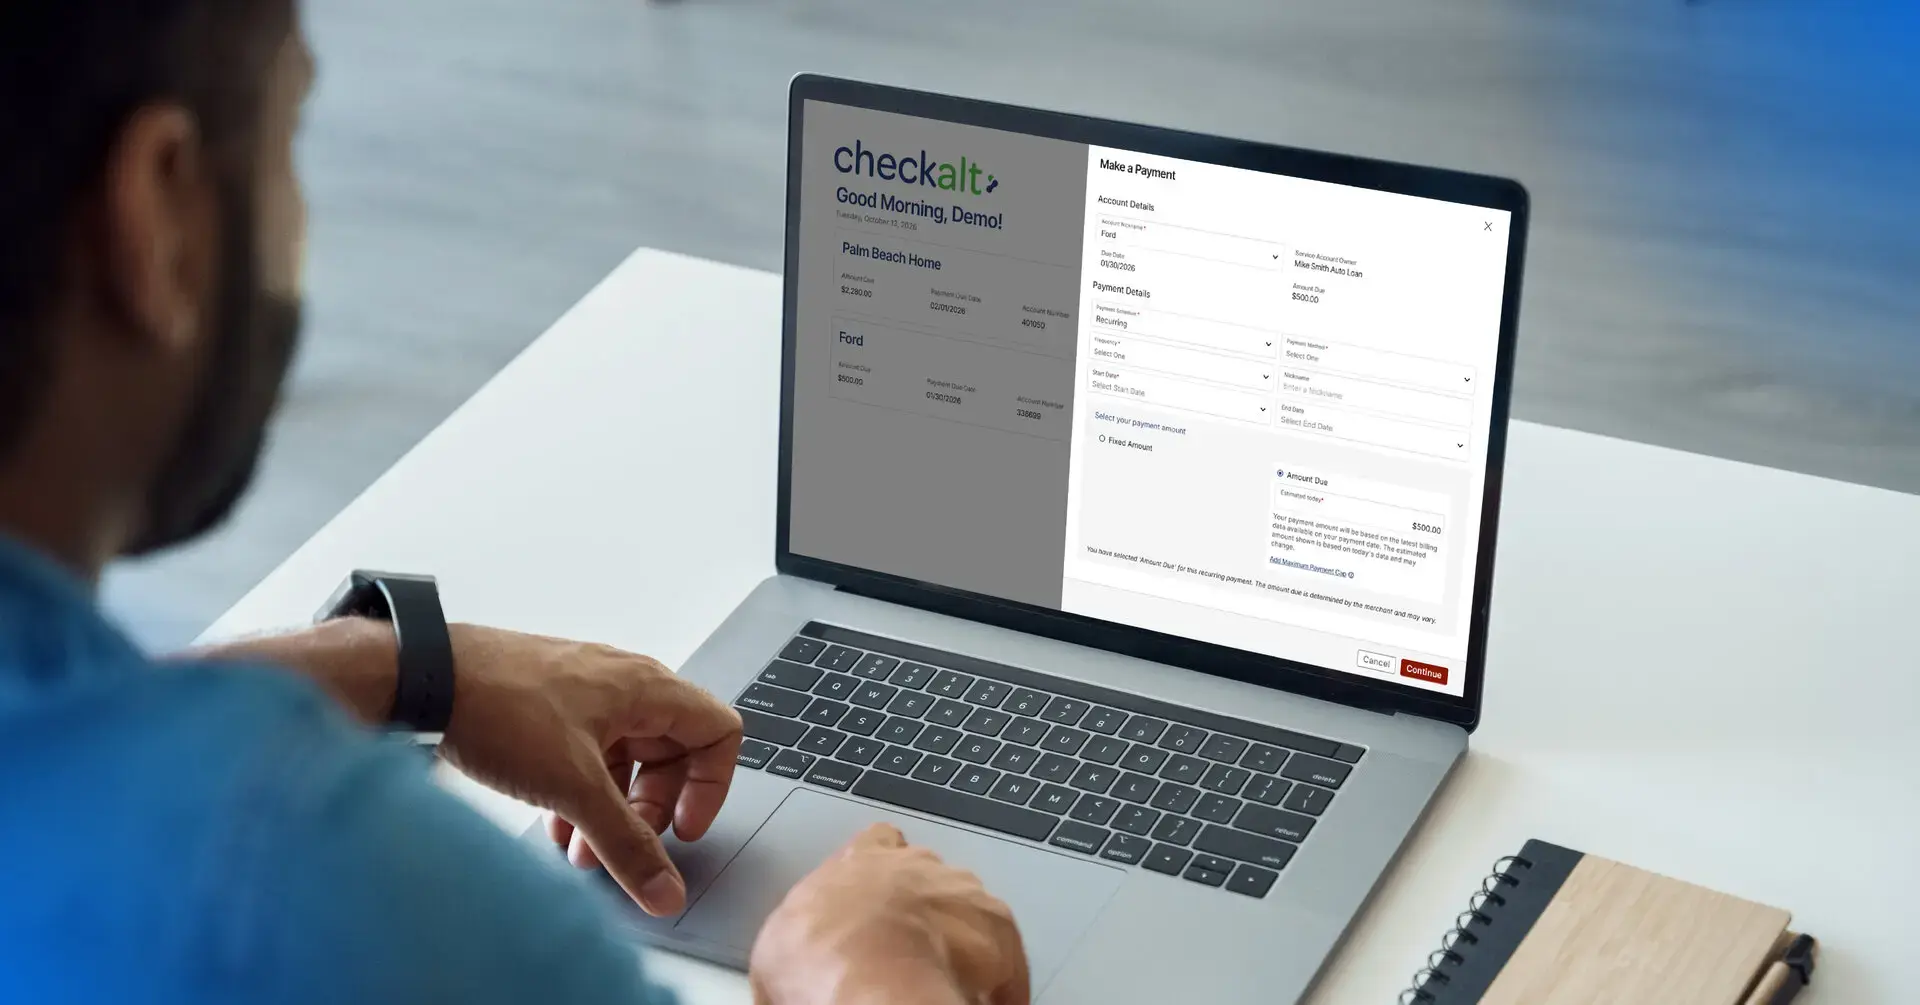
Online payments are electronic transactions that allow individuals or businesses to make payments through a website, payment portal, or other digital channel using methods such as ACH transfers, electronic checks (eChecks), debit cards, and credit cards.

Online payment solutions typically provide a secure interface for initiating transactions, processing payments, and accessing payment information. Depending on the platform, they may also support recurring payments, transaction reporting, and integration with existing financial systems.

For organizations that manage a high volume of incoming payments, these capabilities can simplify the payment experience while supporting more efficient receivables operations.

Understanding Common Online Payment Methods

Not all digital payments work the same way. Different payment methods offer distinct advantages depending on the transaction type, payment amount, and needs of the payer and organization.

ACH Payments

Automated Clearing House (ACH) payments move funds electronically between bank accounts through the ACH network. These payments are commonly used for bills, loan repayments, and recurring transactions. Because ACH payments don’t require card networks, they can offer a cost-effective option for organizations processing regular or higher-value payments.

ACH transactions are generally processed in batches, with settlement timing depending on the transaction and processing arrangements.

Electronic Checks (eChecks)

An eCheck is a digital payment initiated using bank account information rather than a physical paper check. It typically uses the ACH network to move the funds.

For customers, eChecks provide a familiar payment option for those who prefer paying directly from their checking accounts. For businesses, eChecks can reduce the need to receive, deposit, and process physical checks.

Debit and Credit Card Payments

Debit and credit cards provide another convenient way for customers to make online payments, and they're especially useful for one-time transactions, such as paying an outstanding invoice or making a loan payment with a debit card. They can also be used for recurring transactions where supported.

While card payments may carry higher processing costs than ACH and eCheck, offering them gives customers additional flexibility in how they pay.

How Online Payments Improve Receivables Management

Online payments can also make the work behind payment acceptance easier. From reducing manual processing to improving payment visibility, the benefits extend across the receivables process.

1. Reduce Manual Payment Processing

Paper-based payments often require multiple steps, including mail handling, check preparation, deposit processing, and reconciliation. Online payments eliminate many of these physical activities by allowing customers to initiate transactions electronically.

For organizations managing large payment volumes, reducing manual steps can free employees to focus on exceptions, customer service, and other higher-value work.

2. Make It Easier for Customers to Pay

Payment friction can occur when customers have limited payment options, must navigate complicated processes, or need to contact an organization to complete a transaction.

Online payment portals make it possible for customers to pay from virtually anywhere, without mailing a check or visiting a branch or office. Features such as guest payments, multiple payment methods, and recurring payment options can further simplify the experience.

For lenders and credit unions, purpose-built online loan payment solutions can also address needs such as serving indirect borrowers who may have a loan but no deposit account or established digital banking relationship with the institution.

3. Improve Payment Visibility and Reporting

Knowing when a payment was initiated, its processing status, and whether it requires attention is essential to effective receivables management.

Online payment solutions can give finance and operations teams centralized access to transaction details, payment status, and reporting, making it easier to monitor incoming payments and identify items that require attention.

4. Simplify Reconciliation and Exception Management

Once a payment is received, it still needs to be matched to the right customer account, invoice, or loan. Without effective reporting and integration, adding online payment methods can create additional reconciliation work.

For example, when a payment arrives without the information needed to identify the customer or outstanding balance, someone may have to research it manually before it can be posted. Online payment solutions that provide detailed transaction data and connect with existing receivables workflows can help teams identify discrepancies, manage exceptions, and reduce manual research.

How a Credit Card Provider Modernized Its Payment Experience


See how a credit card provider replaced its resource-intensive, in-house payment portal with CheckAlt’s Online Payments solution, reducing manual work, strengthening security, and improving the customer experience.

Read the Case Study

What to Look for in an Online Payment Solution

Not all online payment platforms provide the same capabilities. When evaluating a solution, organizations should consider both the customer payment experience and the operational requirements behind it. Key questions include:

  • Does it support multiple payment methods? Offering ACH, eCheck, debit, and credit card options allows customers to choose the payment method that works best for them.
  • Can customers make one-time and recurring payments? Flexibility is important for organizations that collect both occasional and regularly scheduled payments.
  • How easy is the payment experience? Hosted payment pages, straightforward workflows, and guest payment options can help reduce unnecessary barriers.
  • What reporting and visibility are available? Teams need access to transaction details, payment statuses, and information that supports reconciliation.
  • How does it fit into existing systems and workflows? Consider how payment information will move between the payment platform and the organization’s accounting, loan servicing, or receivables systems.
  • How are security and compliance addressed? Look for appropriate safeguards for sensitive payment information, including encryption, access controls, and relevant industry compliance requirements.

The right solution should make payments easier for customers without introducing unnecessary complexity for internal teams.

Connecting Online Payments to a Broader Receivables Strategy

Many organizations still receive payments through a combination of electronic and paper-based channels. For example, different customers may pay online, mail a check, use their financial institution’s online banking bill pay service, or submit payments through other methods.

Managing these payment streams separately can create fragmented reporting, inconsistent workflows, and additional reconciliation work. That’s why online payments are most effective when considered as part of a broader integrated receivables strategy.

By connecting online payment acceptance with capabilities such as lockbox, electronic lockbox, and remote deposit capture, organizations can gain a more complete view of incoming payments while reducing the complexity of managing multiple channels.

A more connected approach helps organizations manage incoming payments efficiently, regardless of how customers choose to pay.

Simplify Receivables with CheckAlt

Online Payments is part of CheckAlt’s broader integrated receivables solution, which enables organizations to manage digital and paper-based payment channels through a more connected approach.

Ready to simplify how your organization accepts and manages payments?

Explore CheckAlt’s Online Payments solution to learn how flexible digital payment options can support your receivables strategy.

Online Payments Explained: How Digital Payment Options Support Receivables

Online Payments Explained: How Digital Payment Options Support Receivables

Online payments are a standard part of how consumers and businesses pay bills, invoices, loans, and other obligations. Whether paying a utility bill,...

Read More
AI in Payments and Receivables: Where Should Financial Institutions Start?

AI in Payments and Receivables: Where Should Financial Institutions Start?

AI has quickly become a priority for many financial institutions. The pressure to figure out where AI fits is real, but that can lead teams to start...
Read More
Beyond Lending: How Receivables Can Help Credit Unions Grow Business Relationships

Beyond Lending: How Receivables Can Help Credit Unions Grow Business Relationships

Credit unions looking to grow business-member relationships should think beyond the initial lending relationship. The way they support receivables...

Read More